
Savills IM: European real estate debt finds its moment
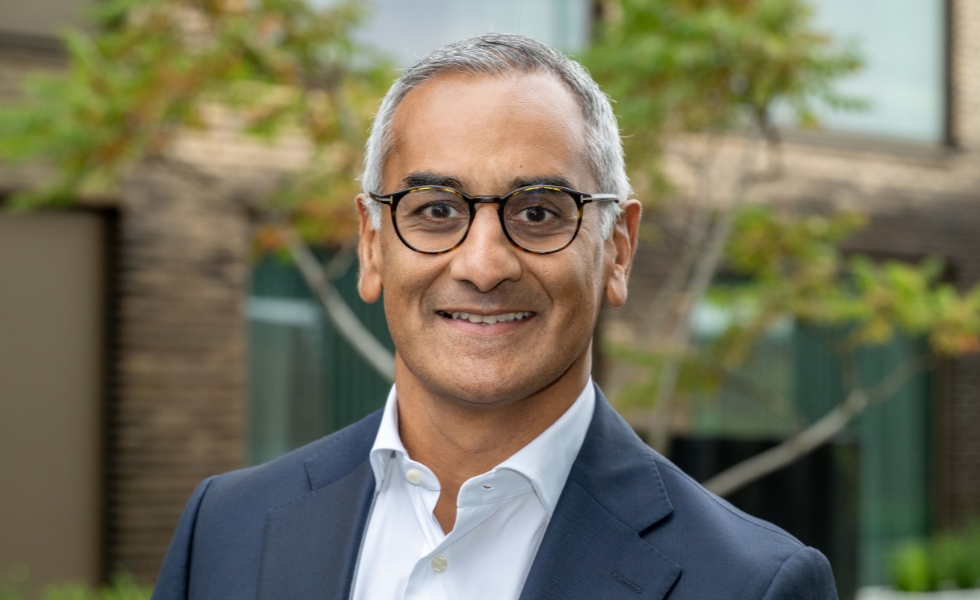
Cyrus Korat, Managing Partner at DRC Savills Investment Management, discusses the opportunities in the European real estate debt market and explains why he believes the asset class currently offers attractive returns, strong downside protection and diversification benefits. ‘The opportunity is both cyclical and structural.’
By our editorial team
How do you view the current state of the private debt market? Are recent developments in corporate lending changing the way investors approach the asset class?
‘Private debt has been one of the fastest growing investment strategies of the last few years. Within private debt, lending to corporates has been by far the dominant growth driver reaching an estimated total AUM now exceeding € 2 trillion. With credit issues historically low and returns that have significantly exceeded public forms of credit, it’s not difficult to see its appeal.
A series of high profile defaults that resulted in substantial credit losses has drawn significant investor attention. Rising levels of payments-in-kind (PIK), increasing defaults and a lack of transparency have emerged as key areas of concern. Some investors (particularly retail) have seen enough, and fund redemptions have risen accordingly. With general concerns about the corporate credit cycle rising, investors have started to look at alternative credit strategies, bringing European real estate debt increasingly into focus.’
What is shaping the opportunity for lenders in European real estate debt today?
‘The European real estate market looks quite different from what we expected at the start of the year. Many anticipated falling interest rates supporting a broad real estate recovery in 2026. Instead, renewed inflation and geopolitical tension have pushed longer-term rates up by around 50bps and the market is now pricing sustained higher rates. That said, we remain broadly within the range we’ve occupied since 2022, so for real estate fundamentals this is not a regime change. Recovery impetus has been paused not reversed.
What we believe makes today’s lending opportunity compelling is that real estate has now been through its reset. Values have contracted – quite sharply in some sectors – and are now showing clear signs of stabilising. For lenders, that is an attractive entry point. New loans are written against rebased values, with lower Loan-to-values (‘LTVs’) and a deeper equity cushion beneath them. We can characterise the opportunity in real estate debt as both cyclical and structural. Cyclically, credit vintages originated today should perform strongly in our view. Structurally, banks continue to retreat under tightening regulations, creating demand for non-bank lending, just as a sizeable wall of debt written in the low-rate environment around the pandemic comes up for refinancing.’
What are the defining characteristics of private real estate debt as an asset class and how do they differ from lending to corporates?
‘At its core, real estate debt is lending secured against a tangible, physical asset. That single feature drives most of the differences from corporate lending, which is typically secured against a business, its cash flows, and often intangible assets. One of our key risk metrics is LTV: we typically lend at ~50-70%, so there is a substantial layer of borrower equity absorbing any fall in value before our loan is touched.
Corporate direct lending is instead sized on a multiple of earnings. That can leave leverage looking artificially low and potentially quick to rise: multiples get stretched in competitive markets, EBITDA can be flattered by adjustments, and if earnings fall, a loan quickly becomes far more leveraged than when it was written. And this is where transparency in the markets diverges. Those earnings adjustments are hard to verify from the outside, and private credit marks are typically manager-determined, whereas property is independently valued by third parties on a regular cycle. Another point to make here is on loan structure. Real estate loans typically carry meaningful value and income covenants, while it appears much of corporate private credit has become covenant-lite.’
If a loan does run into trouble, how does the downside protection compare?
‘This is where the hard asset really earns its place. As a senior lender secured by a mortgage, we have a clear, enforceable path to a building that retains value even in a stressed market, as well as protection where the borrower cannot move or strip the asset without our consent. Strong value and income covenants give us another advantage of early warning if credit quality starts to deteriorate. Corporate lenders, by contrast, are secured against intangible assets and cash flows that can fall away with the business itself. Covenant-lite structures can strip out the triggers for early intervention and delay the chance for action until losses have already materialised.’
How do the returns of real estate debt compare with the wider private credit market?
‘The headline is that real estate debt today offers returns comparable to – and in some instances better than – corporate private credit, but with genuine security beneath it. Our strategies are currently targeting net returns of around 7–9%, with a cash yield of roughly 7%. What’s more telling is the divergence in how returns in these markets have moved. Corporate credit spreads have compressed materially amid an influx of capital and intense competition, while real estate lending margins have held steady. The relative value has moved in real estate’s favour.’
That compression has coincided with a run of high-profile defaults in corporate private credit, resulting in substantial losses for some investors. Rising levels of payment-in-kind (PIK) income, increasing defaults, and a lack of transparency in underlying loan books have all drawn scrutiny, and retailoriented vehicles in particular have seen a rise in redemptions as a result. Real estate debt sits apart from that story.’
Do you see real estate debt as part of a real estate allocation or as part of a broader private credit allocation?
‘In truth, it can sit in either and we see it accessed through both. Some investors come to it through their real estate allocation, drawn by the consistent income and relative return versus real estate equity and the position in the capital stack that debt offers which provides a higher probability of earning its target return. Others hold it within a private credit or fixed-income allocation, attracted by its credit-like return and the more transparent nature of the underlying security. I’d encourage investors not to get too caught up in the label, though. The more useful view is what the asset actually does: it combines the return profile of private credit with the security of real estate. That is also why it complements rather than duplicates. Its returns are driven by property fundamentals and tangible collateral, not corporate earnings. So within a broader private credit allocation it acts as a diversifier, while offering the downside protection that equity real estate alone does not.’
|
SUMMARY European real estate has undergone a substantial valuation reset, creating attractive conditions for new lending. Lower LTVs and larger equity cushions strengthen downside protection. Tangible collateral, independent valuations and covenants offer greater transparency than corporate private credit. Target returns of around 7–9% remain competitive as corporate credit spreads compress. Bank retrenchment and refinancing needs create structural opportunities for non-bank lenders. Real estate debt can diversify broader private credit allocations. |